Use two separate classification questions
First ask what the REIT does: own real estate, finance it, or combine activities. Then ask how the investment is offered and traded. A listed equity REIT and a non-traded equity REIT can own similar buildings but give investors very different liquidity and price-discovery experiences. Publicly traded, public non-listed and private are distribution and market-access categories. Apartment, industrial and office are property categories. Mixing these axes hides important risks.
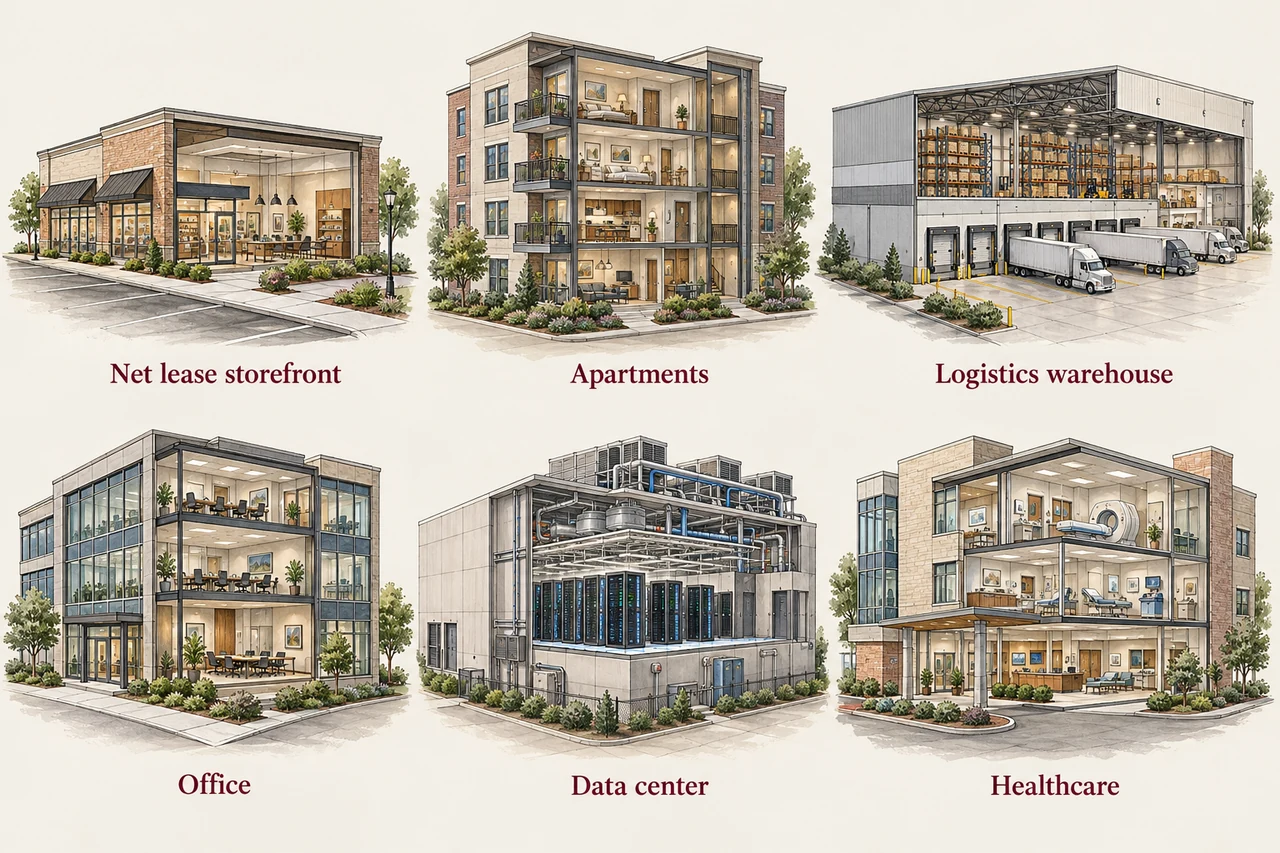
Listed shares make price changes visible
Listed REITs trade on an exchange and file public disclosures. Prices respond to interest rates, expected rent growth, financing conditions and investor sentiment. Daily volatility can be uncomfortable, but it also provides an observable price at which other investors are willing to trade. That price is not an appraisal and does not necessarily equal the company's net asset value. Bid-ask spreads, market conditions and order size can affect the actual execution price.
Non-traded does not mean low-risk
Public non-listed REITs have public reporting obligations but their shares do not trade on a national securities exchange. Repurchase programs may have limits, gates, discounts or suspension provisions. Private REITs can have more restricted access and less public information. Infrequently updated values may look smoother than listed share prices while underlying properties still face the same vacancies, repair bills and debt maturities. Read redemption terms instead of assuming an exit will be available.
Compare the net experience, not just advertised income
One investor may prioritize exchange liquidity; another may accept illiquidity for a particular strategy. The useful comparison includes all fees, leverage, valuation procedures, distribution funding and the realistic holding period. A distribution funded in part from offering proceeds or borrowing does not carry the same implication as recurring operating income. For every vehicle, read the prospectus or offering documents and financial statements. Understand whether the quoted distribution rate reflects a purchase price, an estimated NAV or another denominator.
Hypothetical: a redemption limit
An investor holds $20,000 in a vehicle and requests a full redemption. If only $4,000 of that request is accepted under the program's terms, the investor still has $16,000 invested and exposed to subsequent valuation changes. This is a liquidity illustration, not a description of a specific REIT's repurchase policy.
A common mistake
A stable published NAV or a regular distribution is not evidence that an investment can be sold quickly at that value.
What to check in the disclosures
- Locate the actual repurchase and suspension provisions.
- Distinguish upfront, recurring and performance-related fees.
- Read how distributions were funded.
- Check the age and methodology of the reported valuation.
Sources & scope
This guide focuses on US REITs. Examples are hypothetical unless explicitly attributed. Definitions and issuer disclosures can change; use the current source and the issuer's own reconciliation.
Educational material, not a recommendation or personalized investment advice. How these guides are prepared · Report a correction