A structure, not a single business
A real estate investment trust is a company that owns, operates or finances income-producing real estate. In the United States, REIT tax treatment comes with tests covering assets, income, ownership and distributions. The label does not tell you whether the company collects apartment rent, leases warehouses or holds mortgage securities. Begin by identifying the actual business. An equity REIT generally owns properties; a mortgage REIT generally supplies real-estate financing. Their cash-flow drivers and useful analytical measures differ.
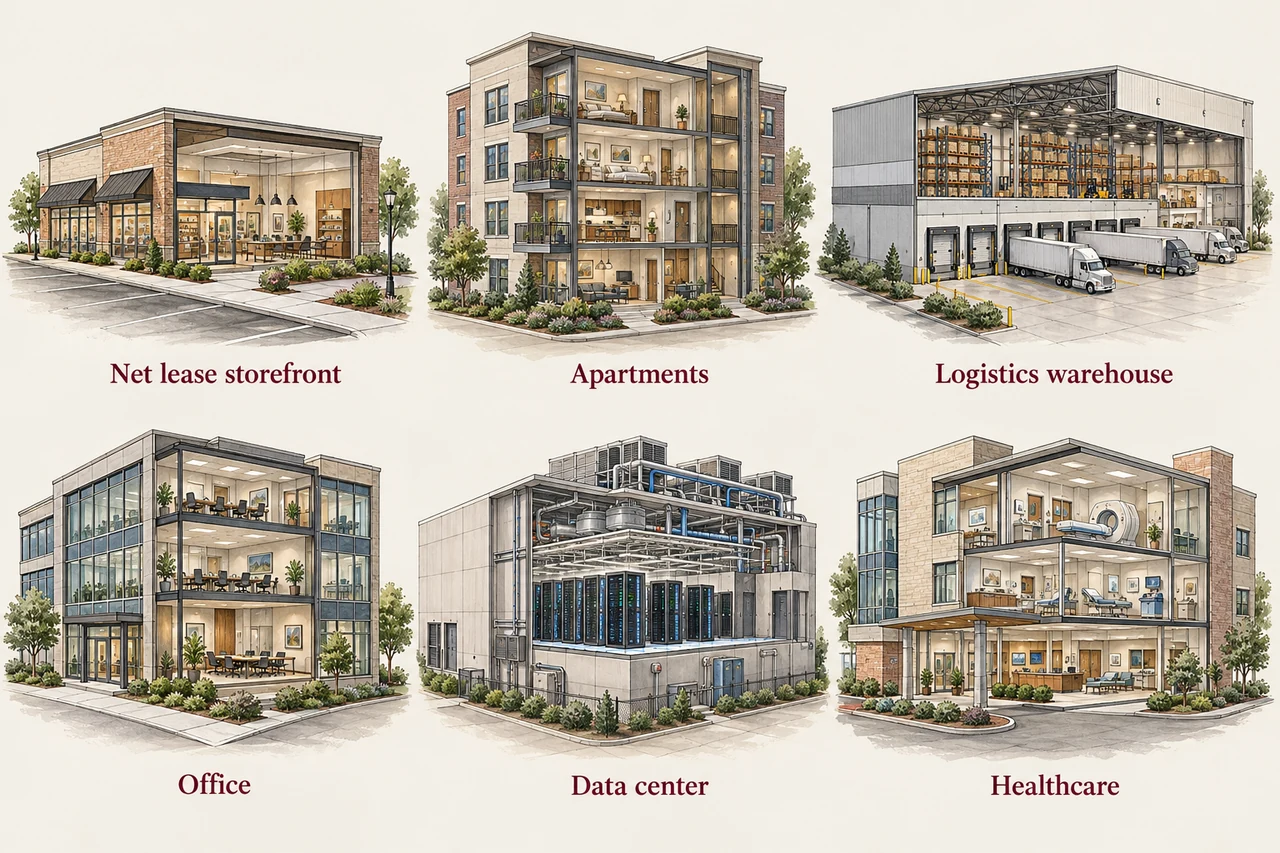
What a shareholder actually owns
Buying a listed REIT share gives you an equity claim on the company, not title to a particular apartment or a right to a particular tenant's rent. Property expenses, interest, corporate overhead, reinvestment and other claims come before cash available to common shareholders. A stock exchange makes shares tradable during market hours, but the quoted price can be far below an estimate of underlying property value. Liquidity is the ability to transact, not protection against a loss.
Why the distribution rule does not insure the dividend
The familiar US requirement generally concerns distributing at least 90% of REIT taxable income, excluding net capital gains, subject to applicable rules. Taxable income is not rent, revenue, GAAP net income, FFO or AFFO. Management may distribute more than the minimum, and a historical dividend may become unaffordable. Accounting depreciation is one reason taxable income and operating measures can differ. A dividend payment is therefore evidence of a payment, not proof that recurring operations funded it.
Two reasonable ways to look at the same REIT
An income-focused reader may value recurring rent and regular distributions. A balance-sheet-focused reader may worry about refinancing, tenant concentration or the equity needed to fund growth. Both can be right. Long leases may stabilize current revenue while delaying the ability to raise rents. A useful first review pairs the business description with the debt note and cash-flow statement. Then examine the issuer's reconciliation of its chosen performance measures, rather than comparing a headline yield in isolation.
Hypothetical: rent is not the dividend
Suppose properties collect $100 of rent, incur $30 of operating costs, and the company pays $15 of interest and overhead. That leaves $55 before capital spending and other items. If recurring improvements require $10, the simplified remaining amount is $45. A $50 distribution would require another funding source in this example. This cash illustration is neither a tax calculation nor a complete FFO reconciliation.
A common mistake
A 7% quoted yield does not mean that rent, earnings or your investment value will grow 7%. Price losses and dividend reductions can outweigh income.
What to check in the disclosures
- Identify equity ownership versus mortgage financing.
- Read the property mix and largest tenant exposures.
- Compare the dividend with a reconciled, appropriate operating measure.
- Inspect recurring capital needs and debt due over the next few years.
Sources & scope
This guide focuses on US REITs. Examples are hypothetical unless explicitly attributed. Definitions and issuer disclosures can change; use the current source and the issuer's own reconciliation.
Educational material, not a recommendation or personalized investment advice. How these guides are prepared · Report a correction